For most small businesses, I’d start with the Square Reader for Contactless and Chip (2nd Generation): its phone-connected setup keeps mobile payments straightforward without adding a full terminal. The SumUp Plus is another compact choice for smartphone-based checkout, while the Square Terminal suits businesses that want a dedicated device with a display and receipt printing. The main tradeoff is between a lightweight reader that depends on a phone and a larger POS terminal that can handle more of the checkout process on its own. I also compare specialist magnetic-stripe readers and other Square handheld options, since their acceptance methods and workflows differ. Read on for the full breakdown and help matching a reader to how your business actually takes payments.

Get smart everyday buys delivered free with Prime
- Fast, free delivery on millions of items
- Prime Video, Amazon Music and more included
- Member-only deals all year
Key Takeaways
- Square Reader for Contactless and Chip (2nd Generation) is the clearest fit for businesses seeking a compact reader that pairs with a phone rather than a standalone POS.
- SumUp Plus offers a similar phone-connected approach, so the choice between these small readers should hinge on the payment setup and service ecosystem that suits your business.
- Square Terminal is a different class of device: it makes more sense when a dedicated screen and receipt printing matter more than pocketability.
- The two Symcode magnetic readers are specialized tools, not direct substitutes for a general-purpose contactless-and-chip reader; check the payment methods your customers use before choosing one.
- Dejavoo QD2 and Square Handheld sit closer to dedicated mobile terminals, making them more suitable for businesses that need a self-contained checkout workflow than for occasional phone-based payments.
| Dejavoo QD2 Mobile Wireless Payment Terminal |  | Best Standalone-Style Terminal | Payment methods: EMV chip, NFC | Display: 2.4-inch color LCD with backlight | Memory: 192 MB (128 MB RAM / 64 MB DDR RAM) | VIEW LATEST PRICE | See Our Full Breakdown |
| SumUp Plus Bluetooth Card Reader for Smartphones |  | Best for Smartphone-Based Simplicity | Connectivity: Bluetooth | Compatible devices: Smartphones and tablets | Operating systems: iOS, Android | VIEW LATEST PRICE | See Our Full Breakdown |
| Square Reader for Contactless and Chip (2nd Generation) |  | Best Overall for Mobile Checkout | Compatible devices: Android, iPhone | Power source: Battery powered | Connectivity: Bluetooth | VIEW LATEST PRICE | See Our Full Breakdown |
| Symcode Multi-Function Magnetic Card Reader |  | Best for Custom Card-Reading Workflows | Brand: Symcode | Model: MJ-Q80 | Interface: USB | VIEW LATEST PRICE | See Our Full Breakdown |
| Square Terminal Credit Card Machine and Mobile POS |  | Best for Cordless Checkout with Printed Receipts | Product dimensions: 5.6 x 3.4 x 2.5 inches | Item weight: 14.7 ounces | Manufacturer: Square | VIEW LATEST PRICE | See Our Full Breakdown |
| Symcode 3-in-1 Magnetic, Chip, and NFC Card Reader | | Best for Multi-Format Card Reading | Model: USA-Q80 | Interface: USB | Supported systems: Windows, Android | VIEW LATEST PRICE | See Our Full Breakdown |
| Square Handheld Portable POS and Credit Card Reader |  | Best for Mobile, All-in-One POS Work | Dimensions: 7.04 x 3.12 x 0.62 inches | Weight: 2.11 ounces | Water and dust resistance: Designed to withstand water splashes and dust | VIEW LATEST PRICE | See Our Full Breakdown |
More Details on Our Top Picks
Dejavoo QD2 Mobile Wireless Payment Terminal
The Dejavoo QD2 suits a small business that wants a dedicated terminal for chip and NFC payments, rather than a reader that depends on a phone app. Its backlit 2.4-inch color display gives payment prompts their own screen, while the included power supply covers charging needs. Compared with the SumUp Plus, which pairs with a smartphone or tablet over Bluetooth, the QD2 is presented as a terminal-first option. That distinction may appeal to sellers who prefer a separate payment device, but the listing does not specify phone-free connectivity or battery details. The main hurdle is administrative: a new SwyftPAY merchant account is required before shipping. I’d choose it only if that account requirement fits the business’s payment setup.
Pros:- Accepts EMV chip and NFC contactless payments
- Backlit color display provides on-device payment prompts
- Terminal and power supply are included
- Portable format is suited to taking payments away from a fixed counter
Cons:- A new SwyftPAY merchant account is required before shipping
- The supplied details do not specify battery life or connectivity
- Listed transaction pricing is 2.69% plus $0.10 per transaction
Best for: Small businesses seeking a dedicated terminal for chip and contactless payments and willing to open a SwyftPAY merchant account.
Not ideal for: Businesses that need to keep an existing processor or merchant account, or want clear battery and connectivity details before choosing.
- Payment methods:EMV chip, NFC
- Display:2.4-inch color LCD with backlight
- Memory:192 MB (128 MB RAM / 64 MB DDR RAM)
- Included items:Terminal and power supply
- Merchant account:New SwyftPAY merchant account required before shipping
- Transaction pricing:2.69% + $0.10 per transaction
Our verdict“Choose the QD2 if you want a dedicated chip-and-contactless terminal and are prepared to set up a new SwyftPAY account.”
SumUp Plus Bluetooth Card Reader for Smartphones
The SumUp Plus keeps mobile checkout centered on a device a small business may already carry: an iOS or Android phone or tablet. Its Bluetooth connection and free SumUp app make it a straightforward fit for market stalls, pop-ups, and appointment-based sellers who want a compact reader rather than a full POS terminal. Compared with the Square Reader for Contactless and Chip, it follows a similar phone-paired approach, while the Square listing specifically calls out offline payments for up to 24 hours. SumUp’s stated tradeoff is a 2.6% plus 10 fee per in-person transaction; transaction charges still apply even though the product description says there are no long-term contracts or hidden fees. Skip it if you need a standalone screen or printed receipts.
Pros:- Pairs with iOS and Android smartphones and tablets over Bluetooth
- Accepts major credit and debit cards
- Portable 142 g reader suits mobile checkout
- No long-term contracts or hidden fees are stated
Cons:- Requires a compatible smartphone or tablet and the SumUp app
- Charges 2.6% plus 10 per in-person transaction
- Does not provide a standalone screen or receipt printer
Best for: Solo sellers and small mobile businesses that already use an iOS or Android phone or tablet and want a Bluetooth reader with an app.
Not ideal for: Businesses that need a standalone terminal, built-in receipt printing, or stated offline payment support.
- Connectivity:Bluetooth
- Compatible devices:Smartphones and tablets
- Operating systems:iOS, Android
- Item weight:142 g
- Transaction fee:2.6% + 10 per in-person transaction
- Model:Plus Card Reader
- Color:White
Our verdict“Pick the SumUp Plus if you want a light, phone-paired reader and are comfortable with a fee on each in-person transaction.”
Square Reader for Contactless and Chip (2nd Generation)
The Square Reader (2nd Generation) earns the broadest-use role here by combining chip and contactless acceptance with Apple Pay and Google Pay support in a battery-powered reader that pairs with iPhone or Android devices. For a small business working markets, service calls, or temporary checkout points, its standout distinction is offline payment support for up to 24 hours, which can help when a connection drops—though offline use has a defined limit. Compared with the SumUp Plus, Square explicitly lists offline payments and fraud-prevention and dispute-management tools. Like SumUp, it still relies on a compatible phone or device, so it is not a self-contained terminal like the Square Terminal, which also prints receipts. Choose this reader for flexible mobile checkout, not for an all-in-one counter setup.
Pros:- Accepts chip, contactless, Apple Pay, and Google Pay
- Supports offline payments for up to 24 hours
- Pairs with Android and iPhone devices over Bluetooth
- Includes fraud prevention and payment-dispute management
Cons:- Requires a compatible phone or other device
- Offline payment support is limited to 24 hours
- Does not offer the integrated receipt printing listed for Square Terminal
Best for: Small businesses that take payments on the move, use an iPhone or Android device, and want stated offline payment capability.
Not ideal for: Retailers who need a standalone payment device, built-in receipt printing, or offline processing beyond the stated 24-hour limit.
- Compatible devices:Android, iPhone
- Power source:Battery powered
- Connectivity:Bluetooth
- Battery:1 lithium-ion battery included
- Item weight:5.92 ounces
- Warranty:Limited 1-year
- Offline payments:Supported for up to 24 hours
Our verdict“Choose this Square Reader for phone-based mobile checkout when broad payment support and limited offline use matter more than a standalone screen.”
Symcode Multi-Function Magnetic Card Reader
The Symcode MJ-Q80 is the technical outlier in this group: it reads three magnetic-stripe tracks, SLE4442 and CPU chip cards, and contactless proximity IC cards over USB. That breadth, alongside development libraries and example code, makes it more relevant to a business building or integrating a custom card-reading workflow than to a shop seeking a ready-to-use bank-card payment terminal. Compared with the Square Reader for Contactless and Chip, which is described as accepting consumer payments through a phone, the MJ-Q80 is oriented toward card data and development; the supplied details do not state that it processes standard payment transactions. Its limits matter: magnetic stripes can be read but not encoded, and deeper CPU-card work requires APDU commands. I would skip it for routine checkout.
Pros:- Reads all three magnetic-stripe tracks
- Supports SLE4442, CPU chip, and contactless proximity IC cards
- USB operation does not require an additional power supply
- Includes development libraries and example code
Cons:- Magnetic-stripe cards can be read but not written or encoded
- Deeper CPU chip card development requires APDU commands
- The supplied product details do not describe standard payment processing
Best for: Small businesses or developers integrating magnetic-stripe, chip, or proximity IC card reading into a Windows or Android workflow.
Not ideal for: Retailers looking for a ready-to-use portable bank-card terminal, payment processing, or a reader that encodes magnetic-stripe cards.
- Brand:Symcode
- Model:MJ-Q80
- Interface:USB
- Compatible systems:Windows, Android
- Magnetic stripe support:Reads all 3 tracks; no writing function
- Chip card support:SLE4442, CPU chip cards
- Contactless support:Proximity IC cards
- Security:Triple DES encryption options
- Weight:0.21 kg
Our verdict“Choose the MJ-Q80 for custom card-reading projects, not as a substitute for a consumer-payment reader like Square Reader.”
Square Terminal Credit Card Machine and Mobile POS
The Square Terminal is the most self-contained checkout choice in this batch: it combines payment acceptance with receipt printing and a built-in battery for cordless use. That makes it a stronger fit for a small shop, food stall, or service counter that wants to hand customers a printed receipt without adding a separate printer. By comparison, the Square Reader for Contactless and Chip is lighter at 5.92 ounces and designed to pair with a phone, but it does not list integrated printing. The Terminal’s tradeoff is portability: at 14.7 ounces and 5.6 x 3.4 x 2.5 inches, it is bulkier than a pocketable reader. The product details also leave connectivity and display size unspecified, so I would not choose it without confirming those needs for a particular setup.
Pros:- Accepts major credit and debit cards
- Prints receipts from the same device
- Built-in battery supports cordless use
- Includes fraud prevention and 24/7 phone support
Cons:- Heavier and larger than the Square Reader for Contactless and Chip
- Business-specific Square subscriptions are offered separately
- The supplied details do not specify display size or connectivity
Best for: Small retailers and mobile service businesses that want one cordless device for accepting payments and printing receipts.
Not ideal for: Sellers prioritizing a very lightweight reader, or buyers who need confirmed connectivity and display specifications before purchase.
- Product dimensions:5.6 x 3.4 x 2.5 inches
- Item weight:14.7 ounces
- Manufacturer:Square
- Model number:8.17044E+11
- Battery:1 included lithium-ion battery
- Receipt printing:Built-in
- Date first available:February 12, 2019
Our verdict“Choose Square Terminal if built-in receipt printing and cordless checkout matter more than keeping your payment device as compact as a phone-paired reader.”
Symcode 3-in-1 Magnetic, Chip, and NFC Card Reader
The Symcode USA-Q80 suits small businesses that need to read several kinds of cards from a computer or Android device, rather than run a complete checkout system. It handles magnetic stripe, EMV chip, SLE4442 chip, and NFC cards, giving it broader reading coverage than the Square Reader for Contactless and Chip. USB plug-and-play operation and keyboard emulation can simplify basic data entry, while software mode offers another route for compatible workflows.
This flexibility comes with a narrower payment role: it is a reader, not a standalone POS, and the magnetic stripe function is read-only. Deep CPU chip-card use also requires APDU commands and development, which makes it a poor fit for businesses seeking a ready-to-use checkout. I’d choose it for specialized card-reading tasks, not as a substitute for Square’s payment-focused readers.
Pros:- Reads magnetic stripe, SLE4442, EMV chip, and contactless NFC cards
- Offers keyboard emulation and software reading modes
- USB operation needs no separate power supply or driver
- Includes a two-year warranty
Cons:- Magnetic stripe support is read-only, with no card writing or encoding
- Deep CPU chip-card support requires APDU commands and development
- USB connection limits mobility compared with wireless payment readers
Best for: Small businesses or service desks that need USB-connected reading of magnetic, chip, and NFC cards on Windows or Android.
Not ideal for: Retailers seeking a ready-to-run payment terminal or businesses that need to encode magnetic-stripe cards or use deep CPU chip functions without development work.
- Model:USA-Q80
- Interface:USB
- Supported systems:Windows, Android
- Card types:Magnetic stripe, SLE4442 chip, EMV chip, contactless NFC
- Reading modes:Keyboard emulation and software mode
- Magnetic stripe function:Read-only; does not encode or write
- Weight:210 g
- Warranty:2 years
Our verdict“Choose the Symcode if your business needs broad card-reading formats at a USB workstation, but skip it for mobile checkout or out-of-the-box payment processing.”
Square Handheld Portable POS and Credit Card Reader
The Square Handheld is the better fit when a business needs more than a card reader in a compact, carry-around device. Its barcode scanner, tableside ordering, and support for major credit and debit cards can help staff manage checkout and orders without carrying a separate scanner. The slim, lightweight design and resistance to splashes and dust also suit busy service environments better than the wired Symcode USA-Q80.
Offline payment support can help keep sales moving through a connection interruption, while built-in fraud prevention adds a payment-focused feature set. The tradeoff is that this is a Square POS device, not a simple reader to pair with any preferred system; transaction processing carries a rate, and a protective drop case is optional. I’d favor it over the Square Reader for Contactless and Chip when scanning and order handling matter as much as payment acceptance.
Pros:- Combines card acceptance with a built-in barcode scanner
- Supports tableside ordering and offline payments
- Lightweight, pocketable design with splash and dust resistance
- Includes 24/7 fraud prevention
Cons:- Payment processing involves a transaction rate
- Protective case for accidental drops is optional
- Its POS feature set may be unnecessary for businesses seeking only a basic reader
Best for: Small retailers, food vendors, and service businesses that want one portable Square device for card payments, barcode scanning, and order taking.
Not ideal for: Businesses that only need an inexpensive, simple card reader, want to avoid Square’s transaction processing, or require drop protection included in the box.
- Dimensions:7.04 x 3.12 x 0.62 inches
- Weight:2.11 ounces
- Water and dust resistance:Designed to withstand water splashes and dust
- Payment support:Accepts major credit and debit cards
- Additional features:Barcode scanner, offline payments, tableside ordering, 24/7 fraud prevention
- Manufacturer:Square
- Date first available:May 13, 2025
Our verdict“Pick the Square Handheld if you want a portable Square POS with scanning and ordering tools, but choose a simpler reader if you only need to take payments.”
How We Picked
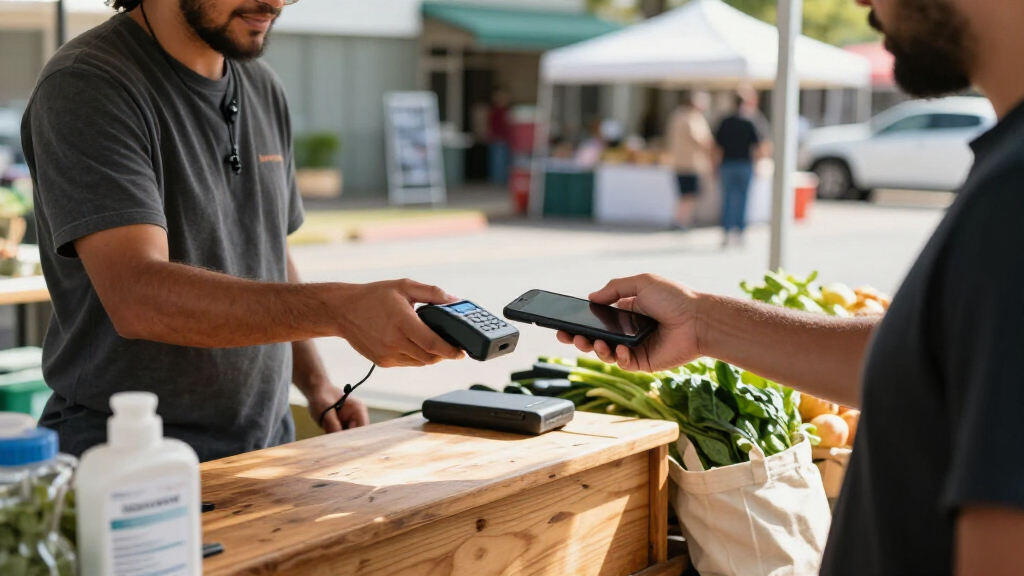
I ranked these portable card readers for small businesses by how well each product fits everyday payment-taking needs: portability, payment-method coverage, ease of setup, and whether it depends on a smartphone or works as a more self-contained POS device. I also weighed the practical impact of each form factor. A small reader can be easier to carry and store, while a terminal with its own interface can reduce reliance on a separate phone during checkout.
The ranking favors flexible, general-purpose options for common small-business situations, then places larger or more specialized devices according to their narrower strengths. That is why the Square Reader and SumUp Plus lead for simple mobile checkout, while the Square Terminal, Dejavoo QD2, and Square Handheld suit different dedicated-device needs. The Symcode readers rank lower for broad everyday use because their magnetic-stripe focus makes payment-method compatibility a more central part of the buying decision.
Factors to Consider When Choosing Portable Card Readers For Small Businesses
Before choosing a reader, I’d map the device to the way customers pay and the way staff take orders. A compact reader is not automatically the best fit if it relies on a phone you need for other work, and a full terminal can add bulk when all you need is an occasional tap or chip payment.
Match Payment Methods to Your Customers
Start by listing the ways customers are likely to present a card or phone, then check that the reader supports those methods. A device centered on magnetic stripes may suit a specific legacy workflow, but it is a poor general-purpose choice if customers expect chip or contactless acceptance. Do not assume that every reader advertised as portable accepts the same payment types. Ask your payment provider about compatibility and any limits before ordering hardware. If you serve a mixed customer base, favor broader acceptance over a device that excels at only one method. This check can prevent the costly mistake of buying a reader that cannot handle your most common transactions.
Decide Whether Your Phone Should Be Part of Checkout
Phone-connected readers keep the hardware small, but they make your payment workflow dependent on a compatible smartphone, its battery, and a working connection where required. A dedicated terminal reduces that dependency and can be easier to hand to staff who should not use a personal phone for transactions. Think about what happens during a busy period if the phone is occupied, low on power, or needed for calls. A shared business device may solve that issue without requiring a larger POS terminal. Check the reader’s app requirements and supported phone models before buying. The best choice depends on whether you value minimum hardware or a checkout tool that operates more independently.
Choose Portability for Your Actual Work Pattern
Portability can mean slipping a reader into a pocket, carrying a handheld terminal between tables, or taking a countertop-style device to a market stall. Those are different needs, so consider how often staff move and how much equipment they already carry. A tiny reader is easier to store, but it may leave order entry and transaction management to another device. A larger unit can simplify checkout in one place while becoming awkward for staff who move through a venue. Common mistakes include buying for occasional events when most transactions happen at a fixed counter, or choosing a countertop-friendly terminal for table service. Match the form factor to the distance between the customer, the staff member, and the main POS station.
Check the Full Payment Workflow, Not Just the Reader
A card reader is only one part of taking payment: the accompanying app or POS system may control inventory, receipts, staff access, refunds, and transaction records. Make a list of the tasks your business needs to complete at checkout, then confirm which device and software handle each one. A basic reader may be enough if you already have a separate system for sales records. If staff need to enter orders, review items, or issue receipts at the point of sale, a dedicated terminal may reduce handoffs. Ask whether the hardware works with the payment service and business tools you already use. Choosing based on the reader alone can lead to duplicate work after the transaction.
Plan for Connectivity, Power, and Busy Periods
Small businesses often use readers in places where connectivity and power are less predictable, such as outdoor markets, pop-ups, or mobile service appointments. Check the required connection method, phone or terminal battery needs, and what the provider says happens if service drops. Do not treat wireless capability as proof that a device can process payments without an internet connection. Consider how long the reader must last during your busiest shift and whether staff can charge it between service periods. A backup plan might mean keeping a charged phone, a power bank, or another accepted payment method available. These practical details matter more on a long event day than a small difference in device size.
Compare Ongoing Fit Before Paying for Extra Hardware
A more capable device can be worthwhile when its screen, receipt handling, or independent operation replaces steps in your current checkout process. It may be unnecessary if your business only takes occasional payments and already has a phone ready to run the payment app. Compare the hardware’s role with the software and payment service you plan to use, including any account or compatibility requirements. Also consider whether your business may add staff, locations, or product tracking soon; a simple setup that cannot grow with those needs can create a second purchase later. Avoid paying for features that will sit unused, but do not choose a bare-bones reader if it forces staff into repeated workarounds. The right spend is the one that fits both today’s checkout and a realistic next step for the business.
Frequently Asked Questions
Should I choose a phone-connected reader or a standalone terminal?
I’d choose a phone-connected reader if you already have a compatible business phone and want the smallest hardware setup. A standalone terminal fits better when staff need a dedicated checkout device or when using a phone for payments would interrupt other work. Consider who will operate it, where transactions happen, and how the device will be charged. Also confirm the required app, connectivity, and payment service before buying. The smaller reader is not automatically simpler if it makes staff rely on a phone they cannot keep available.
Are magnetic-stripe readers enough for a small business?
That depends on the payment methods your customers use and the rules of the payment service you plan to use. A magnetic-stripe-focused reader may suit a narrow or existing workflow, but it should not be treated as a general replacement for a reader that supports chip and contactless payments. Check the exact payment methods accepted by the device and whether your processor permits your intended use. If you are buying your first reader, favoring broader payment coverage can reduce the chance of turning away customers. The Symcode models in this roundup are best approached as specialized options, not default choices for every shop.
Do I need a receipt printer built into my portable payment device?
Not every business needs a built-in printer. If customers are comfortable with digital receipts and your checkout process supports them, a smaller reader may be easier to carry and store. Printed receipts can matter for customers who request paper copies or for workflows where staff need a physical record at the point of sale. Think about the setting as well: a fixed stall or counter may accommodate a larger device more easily than table service or mobile work. Confirm how receipts are issued before choosing a device, since the reader itself may not cover every receipt option.
What should I check before buying a reader for events or outdoor sales?
Check the connection requirements, battery expectations, and whether your phone or terminal will remain available throughout the event. Wireless hardware still may rely on a separate network connection to process transactions, so ask the provider what happens if coverage is weak. Test the planned setup at the actual venue when possible, including the phone app and any account sign-in steps. Pack a charging option and a backup way to take payment if the primary setup fails. A compact reader is useful at events only if the complete phone, power, and connectivity arrangement works there.
When is a larger portable POS terminal worth choosing over a compact reader?
A larger terminal can make sense when you want a dedicated screen, fewer phone-related steps, or additional checkout functions such as on-device receipt handling. It may also suit staff who need a consistent tool they can pass between team members. A compact reader is usually a better fit when payments are occasional or when you already manage orders and records on a separate system. Compare the device’s role with your current workflow rather than choosing by size alone. If the extra functions will not replace a task or solve a real checkout problem, the larger unit may add more equipment than your business needs.
Conclusion
For most small businesses seeking a compact, general-purpose mobile setup, I’d choose the Square Reader for Contactless and Chip (2nd Generation) as the best overall pick. The SumUp Plus is my best value-style fit for businesses that want a small smartphone-connected reader, while the Square Terminal is the best premium-style choice for buyers who want a dedicated screen and receipt printing. Beginners who already have a compatible phone may find the Square Reader’s simpler hardware approach easiest to start with; confirm the app and service fit first. For a more self-contained handheld workflow, compare the Dejavoo QD2 and Square Handheld, and choose a Symcode reader only when its specific magnetic-stripe or multi-method setup matches your payment needs. The right pick comes down to which methods your customers use and whether you want your phone or a dedicated terminal at checkout.
Halloween Picks
halloween
As an affiliate, we earn on qualifying purchases.