TL;DR

Get smart everyday buys delivered free — and shop member deals
- Fast, free delivery on millions of items
- Access to Prime Big Deal Days deals on October 6–7
- Prime Video, Amazon Music and more included
Retirement downsizing is not automatically a financial win: sale and purchase costs, moving expenses and setup costs can absorb much of the price difference. The key calculation is how long lower annual housing costs would take to repay those upfront expenses, alongside the value of staying near familiar people and services.
Retirees weighing a move to a smaller home should compare all one-time moving costs with the new home’s likely annual savings before treating downsizing as a way to free up money, according to the source article. Selling, buying, moving and setting up a different home can consume a substantial share of the apparent price difference, so the decision’s financial value depends on a break-even period as well as personal priorities such as accessibility, community and family ties.
The article recommends adding sale costs, purchase closing costs, movers and expenses such as new window coverings or furniture, then dividing that total by the expected annual reduction in housing costs. The result estimates how many years it takes to break even. It is a planning estimate, not a guarantee: both the upfront total and future savings depend on the specific homes, contracts and circumstances.
For broad budgeting, the article cites Freddie Mac guidance that seller fees and taxes can run 2% to 4% of the sale price, on top of agent commissions that the guide puts at a wide 3% to 8%. Freddie Mac lists typical buyer closing costs at 2% to 5% of the purchase price. These are ranges rather than quotes. Commissions are negotiable, and the article says sellers should rely on the terms of their own agreement rather than assume a standard rate.
The example in the source compares a $450,000 sale with a $300,000 purchase, a $150,000 difference in home prices. Applying the stated transaction-cost ranges, the article estimates roughly $28,500 to $69,000 in transaction costs before moving expenses. Move.org estimates cited in the article put a full-service local move under 100 miles at about $7,600 and a move beyond that distance at $9,140 or more. Individual quotes vary with the home, distance and timing.
The Costs Can Erase Expected Savings
The decision can affect both a retiree’s available cash and monthly budget. A lower purchase price does not by itself establish that a move improves finances: transaction and setup expenses reduce the equity released, while the amount saved each year may be modest. A new home can also bring costs such as a condominium or homeowners’ association fee, which should be included in the comparison.
The source article cites Harvard’s Joint Center for Housing Studies report, Housing America’s Older Adults 2023, for 2022 mortgage figures. It says 41% of homeowners aged 65 to 79 had a mortgage, as did 31% of homeowners aged 80 and older. For owners without mortgages, the article argues, monthly housing expenses may already consist largely of taxes, insurance, utilities and upkeep. A smaller home could reduce some of those costs, but the actual difference must be calculated for the properties being considered.
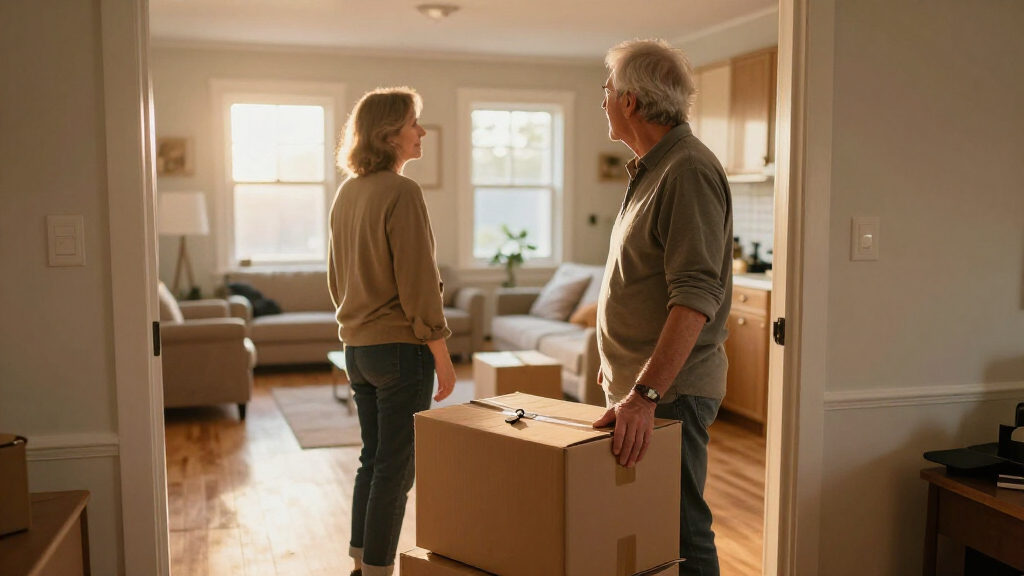
The non-financial consequences also matter. A move can change access to relatives, doctors, pharmacies, familiar services and social connections, while a smaller or more accessible home may better fit someone’s needs. The source’s central point is that the calculation should include the life a person wants to live, not just the home’s square footage or sale price.
As an affiliate, we earn on qualifying purchases.
Many Older Adults Prefer Staying Home
Downsizing is often presented as an obvious response to an oversized home, stairs or maintenance. But the source article cites AARP’s 2024 Home and Community Preferences survey, which found that 75% of adults aged 50 and older said they wanted to live in their current home for as long as possible. That figure describes a stated preference; it does not mean everyone can remain at home or that staying is the right choice for every household.
The article also notes that the move involves two distinct questions: whether the current home remains suitable, and whether selling it for another home makes sense financially. Its suggested approach is to price a specific move rather than rely on general advice. Freddie Mac’s cited transaction ranges are broad estimates, and the article says that, under National Association of Realtors practice changes effective in August 2024, covered listing services may no longer display offers of buyer-agent compensation. Buyers working with an agent generally sign a written agreement setting compensation before touring homes; a seller may still agree to cover some or all of it.
As an affiliate, we earn on qualifying purchases.
Personal Costs and Savings Vary
The cited percentages and cost ranges do not determine what any particular household will pay or save. Actual agent compensation, closing costs and moving quotes depend on the transaction, location and agreements involved. The source does not provide a detailed quote for the example home sale, a specific replacement property, or a defined annual savings figure, so its $28,500-to-$69,000 transaction-cost estimate cannot establish an individual break-even date.
Future maintenance, insurance, utilities, property taxes and association fees can change, and the costs of preparing a home for sale or addressing repairs may differ from one property to another. The source excerpt also does not complete its promised four-step calculation. It is therefore unclear how its approach would account for changes in home values, investment returns on proceeds, taxes or the financial value of accessibility and care needs. Those factors require household-specific estimates rather than assumptions.
retirement home furniture and setup
As an affiliate, we earn on qualifying purchases.
As an affiliate, we earn on qualifying purchases.
Price a Specific Move First
Before listing a home, a household can build a side-by-side estimate for the current property and a realistic replacement. Include sale and purchase expenses, agent compensation under the actual agreements, moving and setup costs, and recurring costs such as taxes, insurance, utilities, maintenance and any association fees. Obtain current quotes where possible, then estimate the annual housing-cost difference.
Divide the estimated one-time move cost by that annual difference to get a simple break-even estimate. Compare it with the expected time in the new home, while also considering the practical reasons to move or stay. The calculation cannot settle those personal choices, but it can show whether the financial case depends on savings that may take many years to recover.
home sale transaction fee calculator
As an affiliate, we earn on qualifying purchases.
As an affiliate, we earn on qualifying purchases.
Key Questions
Is downsizing in retirement always a way to save money?
No. Sale, purchase, moving and setup costs can absorb much of the price difference, and a smaller home’s annual costs may not be much lower. The result depends on the specific properties and household expenses.
How do I estimate the financial break-even point?
Add the one-time costs of selling, buying, moving and setting up the new home. Divide that total by the estimated annual reduction in housing costs. This gives a rough number of years to recoup the expense, not a guaranteed outcome.
What transaction costs are included in the source’s estimates?
The article cites Freddie Mac ranges of 2% to 4% of the sale price for seller fees and taxes, in addition to agent commissions, and typical buyer closing costs of 2% to 5% of the purchase price. It describes these as broad budgeting ranges, not quotes; actual contract terms and local costs vary.
What if my current home is paid off?
A mortgage-free home still has expenses such as taxes, insurance, utilities and upkeep. A smaller home may cost less to run, but the annual savings could be limited and may take time to repay the costs of moving. Compare actual estimates for both homes.
Should personal ties affect the decision?
Yes. The source argues that proximity to family, services and familiar community is part of the decision, alongside costs and accessibility. Financial break-even is one input, not a complete measure of whether a move suits someone’s life.
Source: rss
Halloween Picks
halloween
As an affiliate, we earn on qualifying purchases.