TL;DR
This article explains the confirmed process behind UPI transactions, detailing each step from initiation to settlement. It highlights why understanding this process matters for users and stakeholders.
The core process of a UPI (Unified Payments Interface) transaction involves multiple confirmed steps, from user initiation to final settlement, with key roles played by banks, NPCI, and payment gateways. This detailed breakdown clarifies how digital payments are securely processed in India, impacting millions of users and the financial ecosystem.

Get smart everyday buys delivered free with Prime
- Fast, free delivery on millions of items
- Prime Video, Amazon Music and more included
- Member-only deals all year
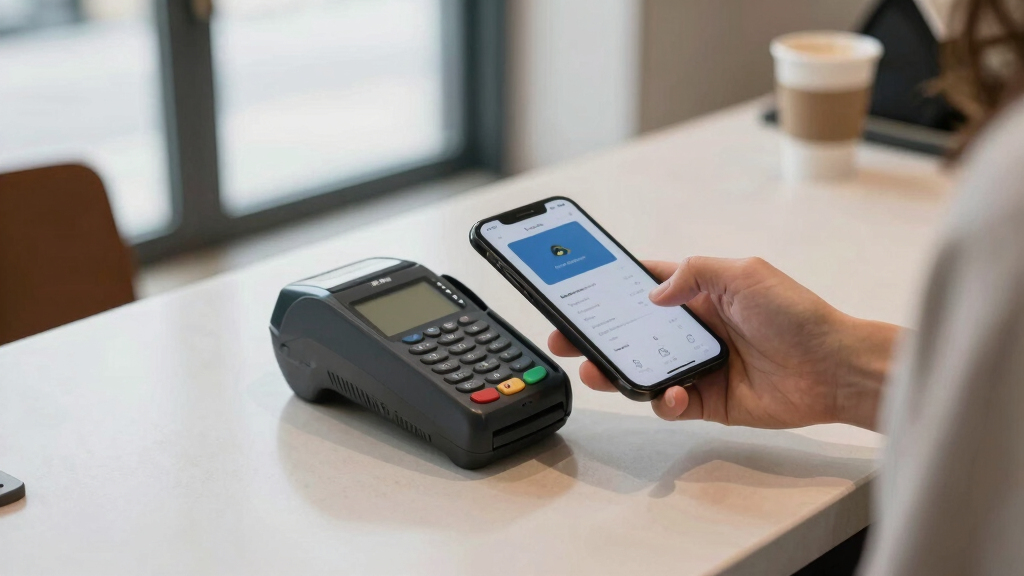
According to recent analyses and official explanations, a UPI transaction begins when a user initiates a payment via a mobile app linked to their bank account. The app sends a request to the NPCI (National Payments Corporation of India), which acts as the central switch facilitating the transaction. The NPCI verifies the details, authenticates the user through secure methods, and forwards the payment request to the payer’s bank. Once the bank authorizes the transaction, a confirmation is sent back through the NPCI to the recipient’s bank, which credits the amount to the recipient’s account. The entire process typically occurs within seconds, ensuring real-time settlement.
It is confirmed that the security of UPI transactions relies on two-factor authentication, including PIN verification and device authentication, which are mandated by RBI guidelines. The NPCI’s role as an intermediary ensures that transactions are processed efficiently and securely, with detailed logs maintained for audit and dispute resolution. Recent disclosures highlight that the entire process involves multiple layers of verification to prevent fraud and ensure data integrity.
Implications of UPI Transaction Mechanics for Users and Banks
Understanding the anatomy of a UPI transaction is crucial for consumers, merchants, and financial institutions, as it underscores the security measures and real-time processing capabilities that have driven widespread adoption of digital payments in India. This transparency builds trust and highlights the robustness of India’s digital infrastructure, which is critical as the country aims for a cashless economy. Moreover, knowledge of these steps can help users better understand transaction statuses, dispute handling, and security features.
Products Worth Considering

Dell XPS Tower 8960 Desktop, Intel Core i7-13700, NVIDIA GeForce RTX 4060, 16GB DDR5, 512GB SSD

LG 27GS60QC-B Ultragear 27-inch Curved Gaming Monitor (QHD, 180Hz, 1ms, 1000R)

Canon PIXMA TR160 Wireless Portable Color Inkjet Printer
As an affiliate, we earn on qualifying purchases.
Recent Developments in UPI Infrastructure and Security Protocols
UPI was launched in 2016 by NPCI and has rapidly become the dominant digital payment method in India, with over 8 billion transactions monthly as of 2023. The system’s architecture involves a central switch operated by NPCI, which connects various banks and payment apps. Recent updates include enhanced security protocols mandated by RBI, such as biometric authentication and transaction limits, to prevent fraud. Industry experts have emphasized that the transparency of the transaction process has contributed significantly to user confidence and system reliability.
“The UPI transaction process is designed for speed and security, with multiple layers of verification that protect both consumers and banks.”
— Ravi Shankar, Payments Expert
What Aspects of UPI Processing Are Still Under Review?
While the overall transaction flow is well-established, details about the handling of disputes, fraud detection during the process, and the specifics of backend verification algorithms remain less transparent. It is also not yet clear how future technological upgrades or security protocols will alter the transaction process, especially with emerging threats and innovations.
Upcoming Enhancements and Regulatory Changes in UPI
The Reserve Bank of India and NPCI are expected to introduce further security features, such as biometric authentication for high-value transactions and AI-driven fraud detection systems. Additionally, ongoing efforts aim to improve transaction speed, reduce failures, and expand UPI’s reach to underserved regions. Industry sources suggest that these developments will be announced in the coming months, with pilot programs already underway.
Key Questions
How secure are UPI transactions?
UPI transactions employ two-factor authentication, PIN verification, and secure encryption, making them highly secure against fraud, according to NPCI and RBI guidelines.
What happens if a transaction fails?
If a UPI transaction fails, the user receives a notification, and the transaction is automatically reversed if it was debited, with details available through the banking app or NPCI portal.
Can a user dispute a UPI payment?
Yes, users can raise disputes through their bank or the UPI app, and the resolution process involves investigation based on transaction logs maintained by NPCI and banks.
Will future updates change how I use UPI?
Future enhancements, such as biometric authentication, aim to improve security and user experience, but the core process of transaction verification is expected to remain consistent.
Source: hn